

Payday Advance Borrow Money

- 194.00 Reviews
- 4.7
- Downloads
- 100,000+
Our take on Payday Advance Borrow Money from Appgk
When an unexpected bill arrives between paydays, the first temptation is to search for the fastest possible answer. Payday Advance Borrow Money is built around that exact moment: it is a free finance app from Shpuryk Sergii that helps users look for a suitable payday cash advance. After spending time with it, my view is fairly clear: it is most useful as a starting point for comparing borrowing possibilities, not as a promise that emergency money will automatically appear in your account.
That distinction matters. The app’s store summary presents it as a way to find an instant cash advance, but a borrowing decision still depends on the lender, the applicant’s circumstances, and the terms shown before accepting anything. I would recommend treating the app as a research and decision-support tool. It can make the search feel more organized, but it should not replace reading the repayment amount, fees, due date, and consequences of late payment.
How the app feels in real financial situations
The basic appeal is speed. Traditional borrowing can involve visiting a branch, collecting documents, or waiting for a bank’s normal review process. A payday advance app aims at people who need to investigate a short-term option from a phone. That makes it relevant for situations such as an urgent household repair, a medical expense, or a bill that arrives before regular income.
In my experience, the most sensible way to use it is before the emergency becomes critical. I would open it with a specific amount in mind, write down the date when I expect to repay it, and compare that plan with the total cost shown during the application process. That small preparation changes the experience from “I need money now” to “Can I realistically repay this on time?”
Best Parts of Payday Advance Borrow Money
Things to Keep in Mind About Payday Advance Borrow Money
The app is listed in the finance category, and its focus is narrower than a full personal-finance manager. It is not the kind of tool I would use to track groceries, build a long-term budget, or monitor investments. Its value comes from helping a user explore a short-term cash advance rather than managing every part of household finances.
One practical strength is that the app is free to install and is suitable for everyone from an age-rating perspective. That makes it easy to try without paying an upfront app charge. Still, free access should not be confused with free borrowing. The cost of any advance comes from the offer and its repayment terms, so I would never judge an option only by the fact that the app itself costs nothing.
News and Features Related to Payday Advance Borrow Money

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
The application has reached over one hundred thousand installs and holds a 4.7 average from roughly three thousand ratings. Those figures suggest that many people have found the app useful enough to rate, but they do not tell me whether every user received an offer, secured the amount requested, or found the final terms affordable. Ratings are a useful signal about usability; they are not a substitute for checking a credit product carefully.
A better way to approach the first screen
With a borrowing app, the first few minutes are important because urgency can make people skim. I would prepare three details before starting: the amount needed, the earliest realistic repayment date, and the maximum total repayment I can handle. If I cannot answer the third question, I am not ready to accept a short-term advance.
Don't want to read the full review?
This method also exposes a common trap. A small amount may look manageable when viewed as a single figure, while the repayment deadline may arrive before the next full pay cycle. I would compare the due date with rent, utilities, subscriptions, and existing repayments rather than looking at the advance in isolation.
Another useful habit is to save or note the offer details before leaving the screen. I would record the amount received, the total to repay, the due date, and any consequences described for missing it. This is especially important when comparing more than one possibility, because memory tends to retain the amount borrowed while forgetting the total cost.
Screenshots
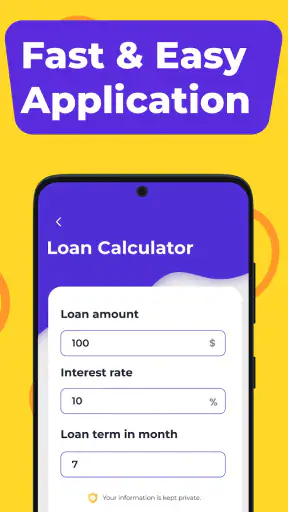
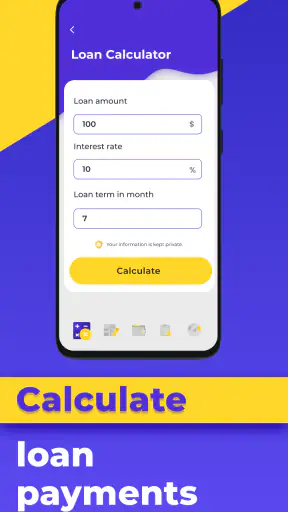
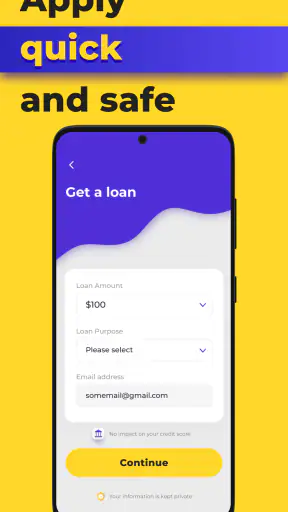
The current release is version 1.2.1 and supports devices running Android 5.0 or later. That broad compatibility is helpful for people using older phones, particularly those who do not want to replace a device just to investigate a financial product. On the other hand, older hardware can make any finance workflow feel less comfortable, so I would use a secure, updated device whenever possible and avoid starting an application on a public or shared phone.
What it does better than ordinary alternatives
The usual alternative is to search the web, open several lender pages, and repeat similar forms. That approach can become confusing, especially when a person is already stressed. A dedicated app gives the search a more focused setting and reduces the need to jump between unrelated pages. For someone who wants to explore a payday advance from a phone, that convenience is the clearest reason to try it.
It can also be more approachable than going directly to a bank. Banks are generally better suited to established customers, planned borrowing, and products designed for longer repayment periods. They may be a better option when the need is not immediate or when a lower-cost personal loan is available. Payday Advance Borrow Money is aimed at a different moment: a short gap that the user believes can be closed quickly.
Compared with asking friends or family, the app offers privacy and independence. That may matter to someone who does not want to explain a temporary cash problem. The trade-off is that a formal advance creates a financial obligation with its own terms. A trusted person may offer more flexibility, while a lender may offer a faster and more structured process. I would weigh both the emotional and financial consequences instead of assuming one route is automatically better.
Compared with a credit card, a payday advance may feel more direct because it is tied to a defined borrowing request. A credit card can be more flexible for repeated purchases, but it can also encourage a balance to linger. Neither option is automatically cheap. The right comparison is the total amount repaid, the time available, and what happens if the repayment plan slips.
The limitation that deserves the most attention
The biggest weakness is not necessarily the app interface; it is the nature of the product it helps users pursue. Short-term advances can solve a timing problem while creating a larger problem later. If repayment depends on another loan, an overdraft, or skipping an essential expense, the app is not solving the underlying shortage. It is moving the pressure forward.
I would be particularly cautious if the same emergency happens every month. In that situation, a payday advance is no longer a one-off bridge. A conversation with a bank, a debt adviser, a utility provider, or an employer about payment timing may be more useful. The app is a poor fit for recurring income gaps, long-term debt consolidation, or any plan that depends on borrowing again to repay the first advance.
There is also a decision-making limitation: an app can present a borrowing route, but it cannot know the full picture of a user’s household budget unless the user carefully supplies and evaluates it. Even a fast approval would not prove affordability. I would never interpret an available offer as a recommendation that I should accept it.
Privacy deserves practical attention too. Finance applications involve sensitive personal and financial information. Before entering anything, I would check that I am using the official application, review the permissions and privacy wording displayed on the device, and avoid sending documents through an unsecured connection. I would also sign out when using a shared phone and remove saved information if the device is no longer mine.
Another point is that speed can encourage incomplete comparisons. The first offer that appears may not be the best one for the user’s situation. I would take a pause, read every repayment line, and compare the total cost with alternatives such as a bank overdraft, an existing credit facility, a payment extension, or borrowing from someone trusted. If the app does not make a term easy to understand, that is a reason to slow down rather than click through quickly.
A realistic everyday example
Imagine that my washing machine stops working two days before payday. I need a modest amount to replace it, and I expect my salary to arrive on schedule. I could use the app to investigate whether a short-term advance is available, but I would first calculate the amount needed after checking whether repair, a used replacement, or a delayed payment is possible.
Suppose the application shows a repayment date close to payday. I would compare the total repayment with the money left after rent, food, transport, and existing bills. If the advance would leave me short for essentials, I would reject it even if the application process were quick. If the amount is affordable and the terms are clear, I would still keep a record of the agreement and set a reminder well before the due date.
That example shows where the app can help and where it cannot. It can make the search more convenient, but it cannot repair the appliance, guarantee approval, or make an unaffordable repayment affordable. The quality of the final decision still comes from the user’s preparation.
Who will get the most from it
I see the strongest fit for an adult who has a genuine, short-lived cash-flow gap, understands the cost of borrowing, and already has a credible repayment plan. The app may also suit someone who prefers researching from a phone rather than contacting several providers separately. Its free availability and support for older Android devices lower the barrier to trying the service.
It is less suitable for someone with unstable income, several existing debts, missed repayments, or no clear date for receiving money. I would also steer away from it if the requested amount is for discretionary spending. A payday advance for a nonessential purchase can turn a moment of convenience into a repayment burden, particularly when the deadline is close.
People looking for budgeting tools, savings automation, credit-building guidance, or detailed spending analysis should choose a different kind of finance app. This application’s purpose is focused on advance borrowing, so expecting it to function as a complete money-management system would lead to disappointment.
Likewise, users who can wait should compare longer-term personal-loan products or ask their bank about alternatives. Those options may involve more paperwork, but extra time can bring clearer affordability checks and a repayment schedule that better matches regular income. The fastest route is not always the least expensive route.
My verdict after weighing convenience against risk
Payday Advance Borrow Money succeeds when viewed honestly: it is a convenient doorway into researching a short-term cash advance, and it may be useful when timing is the main problem and repayment is genuinely secure. The free app, broad Android compatibility, and strong user rating make it approachable for people who want to investigate the category from a mobile device.
My recommendation comes with a firm condition: use it to compare and understand, not to rush. Read the total repayment, confirm the due date, consider what happens if income is delayed, and compare the offer with non-borrowing alternatives. The most important feature is not speed; it is being able to repay without creating a second emergency.
For a one-time, carefully planned gap, I would consider keeping this app in mind. For recurring shortages or uncertain repayment, I would skip it and look for budgeting help, creditor flexibility, or independent debt advice instead. That makes the final judgment balanced: this is a focused finance app with a clear use case, but its usefulness depends far more on disciplined borrowing than on the convenience of the application itself.
Developed by Shpuryk Sergii, the app is free and carries an Everyone content rating, so trying the tool is straightforward. I would still treat every borrowing decision separately from the app’s accessibility. If the terms fit my budget and the need is temporary, it can be a practical place to start. If they do not, the smartest action is to close the application and protect the next payday.
Payday Advance Borrow Money FAQ
What is Payday Advance Borrow Money, and how does it work?
Payday Advance Borrow Money is a short-term borrowing service designed to help users request funds before their next paycheck. After entering personal, employment, income, and banking information, the service may review your application and present available options. Approval, loan amounts, fees, repayment dates, and interest rates depend on the provider and your individual financial profile.
Is Payday Advance Borrow Money a direct lender?
Not necessarily. Services using this type of name may operate as loan-matching platforms rather than direct lenders. They can forward your information to participating lenders, who independently decide whether to approve an application and determine the terms. Before accepting an offer, carefully check the lender’s identity, annual percentage rate, total repayment amount, fees, and privacy policy.
How much money can I borrow, and how quickly will I receive it?
The amount available varies according to your income, employment status, banking history, credit information, and the lender’s policies. Some applications may receive a decision quickly, but approval is not guaranteed. Even after approval, delivery times can differ between standard and expedited transfers, and additional fees may apply for faster funding.
What costs and risks should I consider before applying?
Short-term borrowing can be expensive, particularly when fees, interest, origination charges, late-payment penalties, or optional expedited-transfer fees are included. Missing the repayment date may lead to additional costs, collection activity, or damage to your credit profile, depending on the agreement. Review the complete loan disclosure and calculate whether repayment fits your budget.
What information is required, and is my personal data safe?
Applicants may be asked for identification details, contact information, employment and income records, bank-account information, and permission to verify financial data. Only use the official app or website and review its privacy policy before submitting anything. Avoid services requesting upfront payment to guarantee approval, and never share passwords, PINs, or security codes.











